Chinese low-value and e-commerce exports to the European Union fell by 65% year-on-year in August 2026, providing one of the clearest indications yet that Europe's new customs regime is fundamentally changing cross-border e-commerce flows. The decline follows the EU's introduction of a temporary €3 customs duty on low-value imports and comes after China-to-EU shipments had already fallen 54% year-on-year in July.
The figures, reported by The Loadstar and based on data from Trade and Transport Group, show how rapidly the economics of direct-to-consumer shipping from China are changing. For marketplaces and sellers that built their European operations around inexpensive individual parcels shipped directly from China, the removal of the EU's long-standing customs duty exemption for consignments below €150 has introduced a new cost into a business model heavily dependent on extremely low prices and enormous shipment volumes.
According to Trade and Transport Group managing director Frederic Horst, Chinese low-value and e-commerce exports to the EU dropped 65% year-on-year in August. The contraction accelerated from the already substantial 54% decline recorded in July, suggesting that the disruption is becoming more pronounced rather than representing a temporary adjustment immediately following the introduction of the new rules.
Separate data from Aevean points in the same direction. Its latest figures indicate that China's overall e-commerce exports fell approximately 16% year-on-year in August, the largest decline recorded so far. Europe was the main contributor to that contraction, with Chinese e-commerce exports to the region falling approximately 40%.
The discrepancy between the 40% and 65% figures reflects differences in datasets and measurement methodologies, but both show an exceptionally sharp deterioration in China-Europe e-commerce traffic. Other regions experienced much smaller reductions, while Africa was an important exception, with Chinese e-commerce exports reportedly increasing 71% from a comparatively small base.
The turning point came on 1 July 2026, when the European Union abolished the customs duty exemption previously available for consignments valued at €150 or less. A temporary flat customs duty of €3 now applies to qualifying low-value imported goods and is scheduled to remain in place until July 2028, when the EU expects its broader customs reform and Customs Data Hub to become operational.
Although frequently described as a €3 "parcel tax", the mechanism is more nuanced. The duty is calculated according to the different categories of goods contained within a shipment and their tariff classification. A parcel containing several products belonging to the same relevant category may therefore attract €3, while a shipment containing products falling under several different tariff classifications can generate multiple €3 charges.
For ultra-low-cost e-commerce, even a relatively small absolute charge can substantially change the economics of a transaction. The impact is particularly significant for products costing only a few euros, where customs costs represent a much larger percentage of the total purchase price. This directly challenges the economics that helped Chinese marketplaces build enormous European businesses around inexpensive products shipped individually to consumers.
The EU's decision follows years of extraordinary growth in direct e-commerce imports. According to the European Commission, approximately 5.9 billion low-value e-commerce items entered the European Union during 2025, around four times the volume recorded in 2022.
European authorities argued that the previous €150 customs exemption had become increasingly unsuitable for an e-commerce market handling billions of individual items. The Commission has also raised concerns about undervaluation, customs fraud, product safety and the competitive difference between European retailers importing merchandise commercially and overseas sellers sending products directly to individual customers.
The temporary €3 duty therefore represents only one component of a much broader overhaul of European customs rules. From November 2026, additional Product Identifier requirements are also scheduled to become mandatory for relevant import distance sales, giving customs authorities more information to identify products and detect potentially unsafe or non-compliant goods.
The change is particularly important for Chinese marketplaces such as Temu, Shein and AliExpress, whose international expansion has been closely associated with direct cross-border fulfillment. Trade and Transport Group previously estimated that China accounts for more than 80% of global cross-border e-commerce revenue, with Temu, Shein and AliExpress responsible for the overwhelming majority of Chinese e-commerce exports.
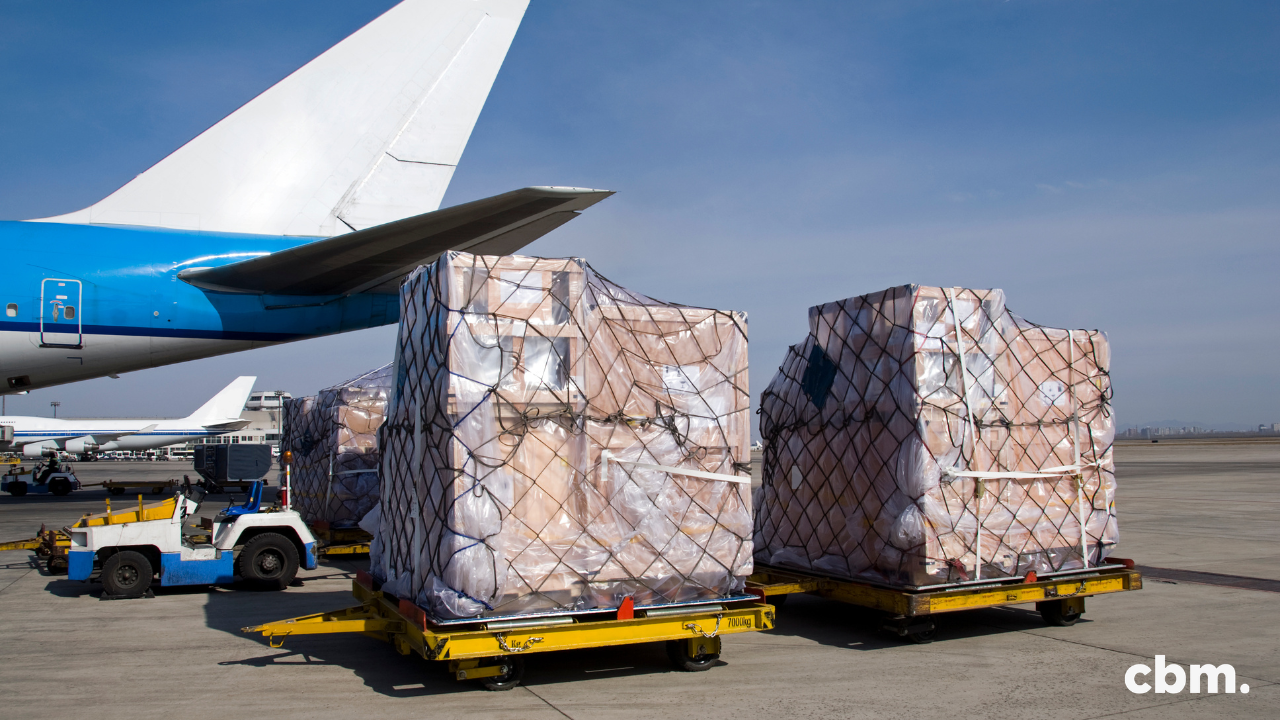
Direct fulfillment from China offered several advantages. Sellers could maintain centralized inventory, avoid duplicating stock across European markets and offer enormous product catalogues without placing every SKU in regional warehouses. Air freight and highly optimized parcel networks then connected Chinese suppliers directly with European consumers.
Europe's new customs environment weakens some of those advantages. The alternative is increasingly to move products into Europe in bulk, clear them through customs before individual orders are placed and fulfill purchases domestically or regionally. This does not eliminate customs costs, but it changes how those costs, inventory and compliance obligations are managed.
The decline in direct parcel traffic does not necessarily mean European demand for Chinese products will disappear. Instead, the regulatory changes could accelerate a transition already underway: moving inventory closer to European consumers.
Chinese marketplaces have increasingly experimented with local seller programs, European warehouses and hybrid fulfillment structures. Under this model, products can be imported in larger commercial shipments, stored within the EU and subsequently delivered as domestic or intra-European orders.
This would represent a fundamental change to the logistics architecture behind Chinese cross-border e-commerce. The competitive battleground would move partially away from ultra-cheap China-to-consumer parcel delivery toward inventory positioning, European fulfillment capacity, last-mile delivery and increasingly sophisticated demand forecasting.
For European fulfillment companies and logistics providers, that transition could create significant opportunities. Marketplace volumes that previously moved directly through airports and postal or parcel networks may increasingly require warehousing, pick-and-pack operations, returns processing and domestic delivery inside Europe.
There are also early signs that European retailers may be benefiting from the changes. Polish fashion group LPP, owner of the Sinsay brand, has linked stronger online growth to the EU's new treatment of low-value imports. Sinsay's online sales reportedly began growing between 20% and 30% from mid-August, with the company pointing to the new import regime as one factor affecting competition from Chinese platforms.
Polish marketplace Allegro has similarly cited reduced competitive pressure from Chinese sellers among the factors supporting stronger domestic performance. The company recently increased its 2026 outlook, including raising its expected Polish gross merchandise value growth to between 11% and 13%.
The situation remains complex, however. Chinese marketplaces are unlikely to simply withdraw from Europe. Their scale, supplier networks, technology and ability to modify logistics models mean that the current decline in direct shipments could eventually be followed by a different type of expansion based on localized inventory and European fulfillment.
The consequences extend far beyond marketplaces and retailers. Cross-border e-commerce has become an important source of global air cargo demand, particularly on routes connecting China with Europe and North America.
Trade and Transport Group estimated earlier this year that cross-border e-commerce represented almost 18% of intercontinental air cargo traffic in 2025 despite accounting for only around 6% of global online sales. The disproportionate impact reflects the industry's reliance on air transport to deliver inexpensive Chinese products to international consumers within competitive delivery windows.
A sustained reduction in direct China-to-Europe parcel traffic could therefore affect freighter demand, airport volumes and airfreight capacity allocation. Major European cargo gateways that developed significant e-commerce operations over the past decade could be particularly exposed to changes in the direct parcel model.
The industry is already adapting. Senior executives from logistics companies including DSV and DHL have highlighted the need for greater flexibility as regulation, geopolitical disruptions and changing e-commerce patterns repeatedly alter global cargo flows. Rather than assuming that established gateways and routes will continue handling the same volumes, logistics companies are increasingly building networks capable of shifting capacity between markets.
The European picture is also not uniform. Chinese e-commerce exports to the United Kingdom declined considerably less than shipments into the EU, according to Trade and Transport Group data.
Volumes to the UK fell approximately 13% year-on-year in August after declining only 5% in July. While still negative, the figures are substantially less dramatic than the 54% and 65% declines recorded for the European Union during the same months.
The divergence provides another indication that regulation is playing an important role in changing shipment patterns. The UK operates outside the EU customs system and is therefore not directly subject to the bloc's new €3 low-value import duty.
The United States provides another example of the ability of Chinese e-commerce networks to adapt to regulatory disruption. Direct low-value shipments from China to the US have reportedly been expanding again since May, although rolling 12-month volumes remain at only around 65% of the levels recorded before May 2025.
The pattern demonstrates how quickly cross-border e-commerce flows can be redirected or reorganized when governments change customs rules. Marketplaces can alter sourcing, consolidate shipments, move inventory into destination markets or develop alternative fulfillment structures.
Europe may now be entering a similar adjustment period.
The 65% decline in August should therefore not necessarily be interpreted as a 65% collapse in European consumer demand for Chinese products. It primarily measures a dramatic contraction in a particular cross-border logistics model: low-value products moving directly from China into the EU.
The distinction is critical. If Chinese marketplaces respond by moving more inventory into European warehouses, some of the lost direct airfreight volume could reappear as bulk freight, ocean shipments or alternative logistics flows. At the same time, local fulfillment would place Chinese marketplaces in more direct competition with European retailers on delivery speed, warehousing efficiency and returns management rather than primarily on cross-border parcel economics.
More regulatory changes are also approaching. The €3 duty is a transitional mechanism expected to operate until July 2028, after which the EU intends to apply normal customs tariffs through its reformed customs infrastructure. New product identification requirements and a planned handling fee will further increase the regulatory and operational requirements associated with selling low-value products into Europe.
Two consecutive months of exceptionally steep declines provide the first substantial evidence that Europe's customs reforms are already influencing international e-commerce flows. A 54% year-on-year contraction in July followed by a 65% decline in August suggests that the impact extends beyond an initial period of implementation.
For Chinese marketplaces, the challenge will be preserving the price advantages that drove their European expansion while adapting to an environment where direct low-value imports no longer receive the same customs treatment. For European retailers, the rules could reduce part of the structural cost difference between locally stocked merchandise and individual products shipped directly from outside the EU.
For logistics companies, meanwhile, the transformation may be even more significant. The extraordinary growth of Chinese cross-border e-commerce helped reshape global air cargo during the first half of the decade. If Europe continues moving away from the direct-parcel model, the next phase of that transformation could increasingly take place inside European warehouses, fulfillment centers and domestic delivery networks.
The 65% decline is therefore more than an e-commerce sales indicator. It may be an early sign that one of the defining logistics models of global e-commerce is being rewritten.

By continuing to use the site, you agree to the use of cookies. more information
The cookie settings on this website are set to "allow cookies" to give you the best browsing experience possible. If you continue to use this website without changing your cookie settings or you click "Accept" below then you are consenting to this.